The topic of inflation and its far-reaching impact on the economy has dominated the news in recent years. And while it’s keenly felt at the gas pump and grocery store, it can have an even more insidious, and often hidden, effect: quietly derailing a retirement plan.
In this article, I discuss what inflation is, why it matters for retirees, and which strategies can help protect your retirement investments over the long term.
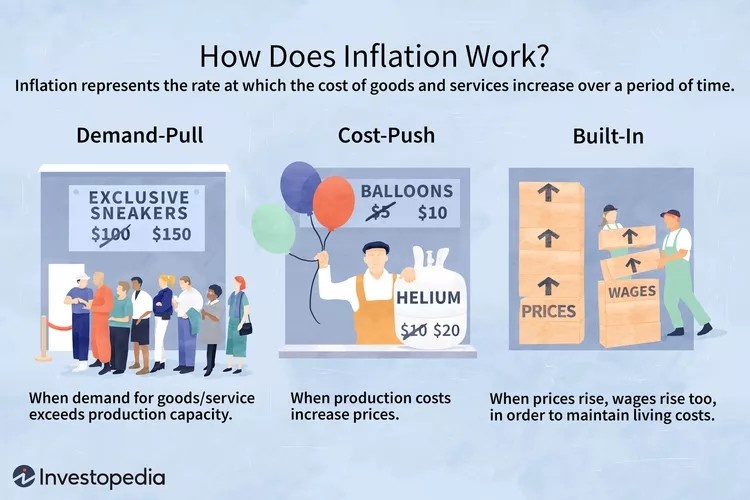
Inflation is the persistent and broad increase in prices, or the decrease in the value of money over time. It is largely influenced by supply and demand.
There are three main types of inflation:
Source: Investopedia
In addition to supply and demand, global events and government policies can accelerate inflationary cycles.
Inflation can’t be traced to a single cause; instead, it usually results from the interaction of multiple economic forces. Below are four key drivers that have contributed to recent inflationary pressures:
While short-term inflation spikes can feel unsettling, proper planning can help keep your 30-year retirement on track. By adopting a risk-management mindset and building a holistic “insurance” framework, you can better protect your portfolio from inflation over the long term.
Here are five ways to minimize inflation’s impact on your retirement investments:
U.S. Treasury Bonds and Notes Ladder Yield Curve
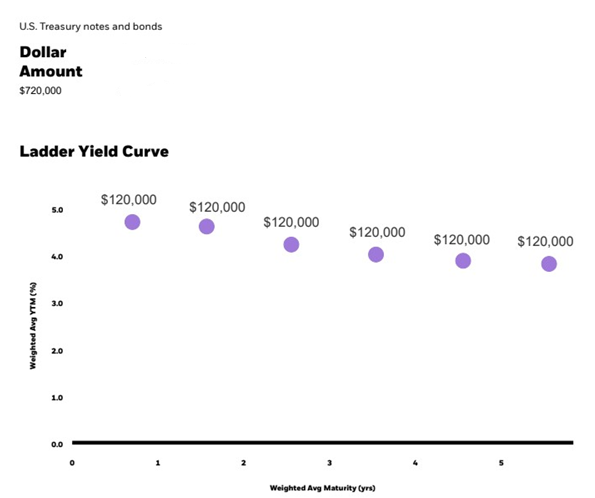
Illustrates how a bond ladder helps reduce inflation-related risk by spreading
$720,000 across six equal Treasury investments with staggered maturity dates.
Bonds provide steady income, but inflation erodes the value of those future payments. To protect your bond holdings, diversify your portfolio by:
Bonds can provide a reliable retirement income; however, fixed-rate bonds alone may not provide enough growth. Complement them with assets that historically outpace inflation.
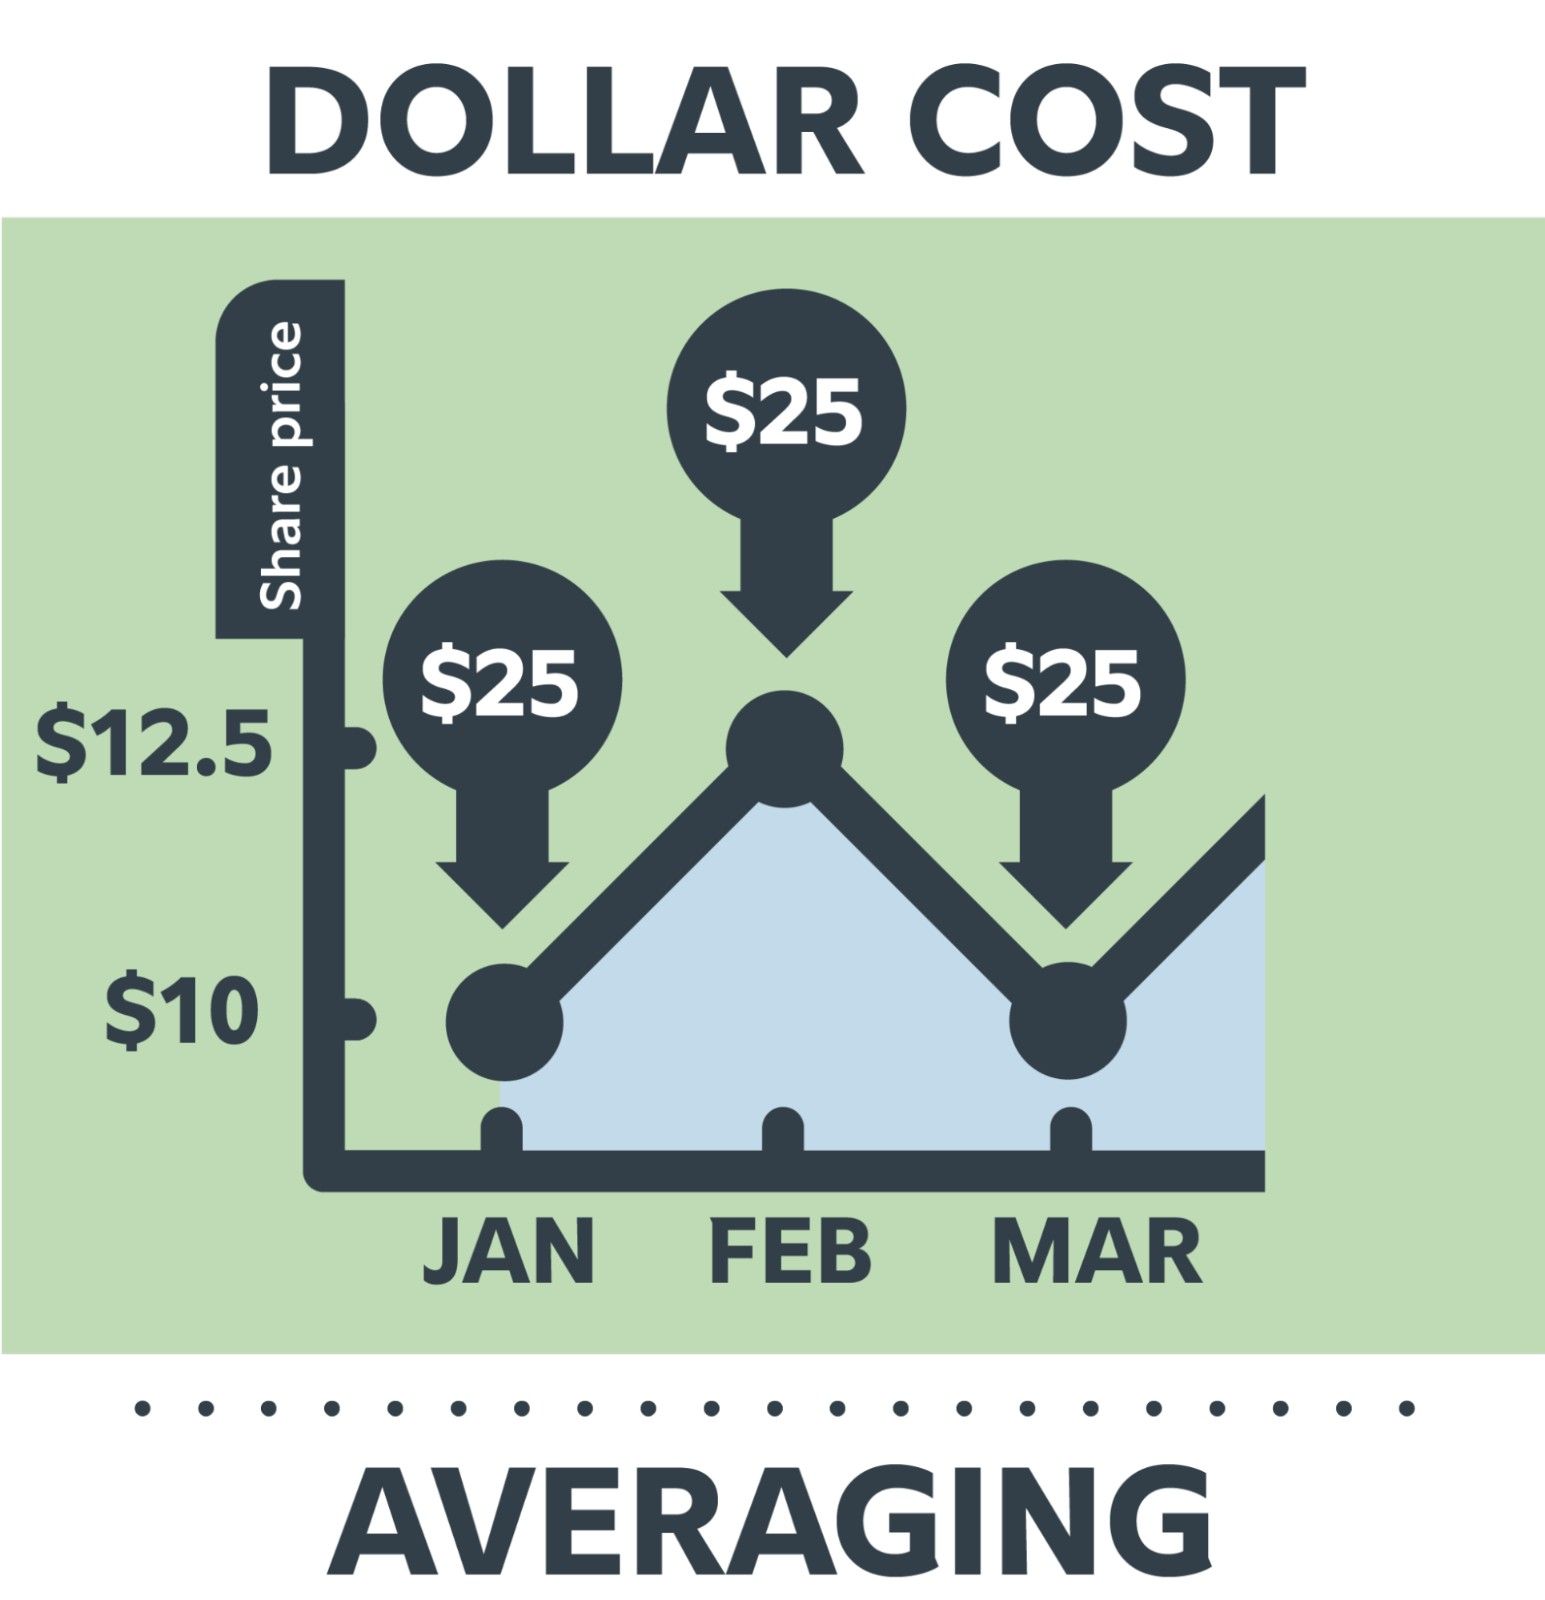
Shows the practice of investing the same amount in regular intervals,
regardless of the current market price
Source: Fidelity
Even well-intentioned investors can make costly missteps during periods of inflation. Here are three common ones to avoid:
We’ve seen how these mistakes can quietly weaken a retirement plan, reinforcing a key lesson: a diversified, well-managed portfolio is your retirement plan’s best defense against inflation and volatility.
Inflation is unavoidable, but it doesn’t have to undermine your retirement. With the right mix of diversified bonds, stocks, and real assets – and a disciplined approach during inflationary periods – you can protect the retirement you’ve worked hard to build. The key is ensuring your plan reflects your goals, time horizon, and comfort with risk.
At Toberman Becker Wealth, we help you see the full picture, align your investments with your goals, and build a portfolio that withstands inflation.
If you are looking for an investment advisor to help you build a sound strategy to support your long-term retirement goals, book a meeting or give us a call.
Craig Toberman is a St. Louis financial advisor and Partner at Toberman Becker Wealth, a fee-only fiduciary firm specializing in retirement planning. The firm helps individuals and families coordinate their investments, tax planning, and retirement income in one financial plan. Craig and the team provide practical guidance for the transition from building wealth to using it throughout retirement.